Forensic File Reviews, Complex Pension Scrutiny and Ongoing Servicing Audits
Second-line quality assurance under COBS, SYSC and the Consumer Duty
Supervisory scrutiny of UK advice files has moved past the tick-box checklist. A forensic review stress-tests complex retirement planning, unpicks non-standard SIPP assets, and identifies balance-sheet liabilities before a thematic visit, a Section 166 appointment or an Ombudsman complaint forces the point.
The standard is the one applied in Financial Ombudsman Service casework, Skilled Person programmes and network supervision. The record is tested under COBS, SYSC and the Consumer Duty (PRIN 2A): was the information complete, was the recommendation suitable, and can the firm evidence the service it charged for?
The notes linked through this page are the detailed tests. This page is how they fit together.
Three lines of a file review
| Complex advice clearance | Due diligence and illiquidity | Ongoing charges and redress |
|---|---|---|
| Presumption against transfer under COBS 19.1.6G | Operator vetting after Adams v Options UK | Fee-for-no-service audits |
| Stochastic models against the TVC hurdle | 30-day liquidity and capital adequacy | Stop-clock fee governance |
| Sponsor covenant and the PPF | SIPP property and the 50% gearing cap | Historical past-business cohort review |
| Algorithmic DBAAT scoring | Decumulation cash traps | Four-tier file grading |
| Abridged advice boundaries | Toxic intermediary funnels | Section 166 redress calculations |
Who the review is written for
Appointed representative networks and principals
Distributed advice practices need an independent second line that can satisfy SYSC and the principal’s own supervisory duties. A network file check that only re-reads the suitability report will not do that.
Directly authorised wealth managers and IFAs
Defined benefit transfers, pension switches and other irreversible recommendations need peer-level clearance before funds move, and extra capacity when a cohort arrives at once.
SIPP operators and discretionary managers
The questions here are asset eligibility, standard against non-standard liquidity, and whether the distribution channel that brought the member in should have been refused.
Compliance directors and SMF16 holders
Second-line testing has to be calibrated enough to stand up to internal audit, a Skilled Person and an FCA supervisory inspection. A grade without a file extract is not that record.
Defined benefit transfers under COBS 19
“Flexibility” is not a reason to overturn the presumption
Under COBS 19.1.6G, the starting point is that a pension transfer is not suitable. Overturning that presumption takes objective, contemporaneous proof that remaining in the ceding scheme produces clear detriment, or fails a critical objective the scheme cannot meet.
The failure mode is treating “flexibility”, “control” or “leaving a legacy” as a substitute for that proof. A client cannot opt out of the suitability rules, and an adviser cannot act as an order-taker for a safeguarded benefit.
The review asks whether the ceding scheme’s own provisions were examined before a flexible alternative was modelled: guaranteed indexation, a spouse’s pension, commutation, and the other features the member would give up.
Baseline scheme audit
Guaranteed benefits and statutory indexation, including spouse's pensions and commutation options.
Then test
Essential income floor
Defined benefit income plus State Pension, set against non-discretionary living costs.
Then test
Alternative solutions
Scheme commutation, cash reserves and life cover in trust, before a transfer is modelled.
Overturn only if
COBS 19.1.6G overturn
A transfer is justified only where keeping the scheme benefit is unviable.
Stress-testing the APTA and the TVC
Under COBS 19.1.2CR, stochastic cashflow modelling may support the advice only where outcomes at the 50th percentile are no less conservative than the deterministic assumptions in COBS 19 Annex 4A and Annex 4C.
The failure is using a median stochastic return to hide early sequence-of-returns risk, or stripping out advice, platform, discretionary and transaction costs — often 1.50% to 2.20% a year — so the pot appears to last five to fifteen years longer than it will. The prescribed TVC hurdle, commonly 5.5% to 8.0% or more net, is set against the net expected return of the proposed portfolio. Projections are run net of all fees, with a downside shock in the early retirement years, and longevity taken out to age 95 or 100.
The full note is Stress-Testing the APTA & TVC: When Stochastic Cashflow Models Cross into “Wishful Thinking”.
Sponsor covenants and the PPF
COBS 19.1.2DG requires information about scheme funding, the employer covenant and Pension Protection Fund entry to be balanced, objective, and supported by specialist expertise.
The failure is using a technical-provisions deficit, or a rumour of corporate restructuring, to move a client out of a guaranteed scheme without an actuarial report or a notice from The Pensions Regulator. The contradiction to look for is a recommendation to transfer from an underfunded scheme whose trustees have already applied an insufficient-assets reduction to the cash equivalent, while the file cites fear of underfunding as the reason to leave.
The full note is Unpacking Scheme Solvency: Handling Employer Covenants and PPF Nuance Under COBS 19.1.2DG.
DBAAT scoring and Section 166 redress
The Defined Benefit Advice Assessment Tool does not grade a narrative. Gate 1 asks whether the firm gathered the information the advice needed. Gate 2 scores the financial trade-offs. At the intersection of attitude to transfer and capacity for loss, capacity for loss wins. Where guaranteed income does not cover essential living costs, capacity for loss is low or zero, and the tool scores the advice unsuitable with detriment, however keen the client was to transfer.
| DBAAT finding | Evidentiary standard | Regulatory and commercial action |
|---|---|---|
| Suitable | Contemporaneous evidence shows retention was unviable, and capacity for loss is robust. | File closed. No action required. |
| Unclear | Gaps in the fact-find or the analysis, without conclusive customer detriment. | Remediation, client contact, and a possible re-audit. |
| Unsuitable (no detriment) | The transfer was unsuitable, but later growth currently matches the notional defined benefit position. | Breach recorded. Liability can return if markets fall. |
| Unsuitable (detriment) | Unsuitable advice and a quantifiable shortfall against the defined benefit rights. | Statutory redress. Pay compensation to restore the member to the notional defined benefit position. |
The full note is The DBAAT File Audit: Scoring Section 166 Redress Liabilities Before the Regulator Arrives.
Abridged advice and full advice
Under COBS 19.1A, abridged advice has two outcomes only: a recommendation not to transfer, or a notification that it is unclear. It is not a soft route into a transfer.
The failure is an unreasonable bridge — a “remain” outcome followed at once by full advice, with no verifiable change in circumstances — or discounted abridged advice used to get around the contingent charging ban in COBS 19.1B. The boundary check is mechanical. Abridged advice does not include an APTA, a TVC or a destination investment mandate, and it is not a basis for a Section 48 confirmation to the ceding trustees.
The full note is Abridged Advice vs Full Advice: Managing the Boundary Under COBS 19.1A.
High-risk SIPPs and non-standard assets
Operator due diligence after Adams v Options UK
In Adams v Options UK Personal Pensions LLP [2021] EWCA Civ 474, the Court of Appeal confirmed that an execution-only disclaimer cannot contract out of Section 27 of FSMA, Principle 2, or SYSC 6.1.1R.
The failure is treating the operator as a passive conduit: a retail transfer into storage pods, agroforestry or another unregulated asset, supported by a member indemnity and nothing else. The review asks whether the investment committee examined legal enforceability, liquidity, title and the distribution channel, and whether it used the duty to refuse the asset before it entered the trust.
The full note is SIPP Operator Due Diligence: Lessons from Adams v Options UK and the FCA Due Diligence Framework.
The 30-day standard asset test
Under the SIPP capital rules, a standard asset has to be realisable within 30 business days for an amount that is certain, or independently verified, without an unreasonable speculative discount. See IPRU-FS 5.2.33R.
Classifying an unquoted bond or an offshore security as standard keeps the capital number down on paper. Reclassified as a non-standard asset, the capital surcharge can remove the solvency margin and trigger a notification under SUP 15.3.11R. The test is the valuation source — an observable price, or a promoter’s own mark — and the disposal record. If real sales took longer than 30 days, the asset is not standard.
The full note is Auditing Illiquidity and Valuation: The 30-Day Standard Asset Test Under SIPP Capital Adequacy Rules.
Commercial property, the 50% cap and connected leases
Section 182 of the Finance Act 2004 caps borrowing for a money purchase arrangement at 50% of the arrangement’s value immediately before the loan. A lease to a connected party has to stay at arm’s length. PTM120000 is HMRC’s starting point for that test.
The failure is measuring the loan against the gross purchase price, or against a future developed value, rather than net assets before the borrowing. A second failure is letting a connected trading company run up rent arrears with no commercial recovery. The review checks that the valuation was dated immediately before completion, that a RICS market rent was on the file, and that the bank statements match the lease. The sanction for getting this wrong is an unauthorised payment charge and a scheme sanction charge.
The full note is SIPP Borrowing & Commercial Property: Navigating the 50% Net Asset Cap and Connected-Party Leases.
Decumulation in a bespoke SIPP
Flexi-access drawdown or an uncrystallised funds pension lump sum, recommended inside a SIPP that is rich in assets and poor in cash, often cannot be paid. The failure is crystallising a commercial property into drawdown without a liquid path to the 25% pension commencement lump sum, or selling the quoted holdings to fund income and leaving an illiquid property as the scheme.
The cash-buffer check is a rolling reserve of about two years’ cash or near-cash, ring-fenced in the SIPP bank account, plus a current valuation for any in-specie movement, and a clear warning about HMRC’s Month 1 emergency tax code (1257L M1) before the first payment.
The full note is Decumulation Friction: Phased Drawdown, In-Specie Transfers, and Illiquid Asset Traps — When It’s Not So Straightforward.
Unauthorised introducers and Section 27
An unregulated lead generator, or a collusive SIPP factory, is a Section 27 problem: the underlying agreement may be unenforceable, and the redress is the member’s loss in full. Onboarding is screened for five repeatable marks.
- Critical. An unregulated lead generator delivering completed SIPP packs. Refuse the business, freeze the relationship, and tell the FCA.
- Critical. Ten or more near-identical cases into the same esoteric asset within days. Stop the pipeline and review the cohort.
- High. Intermediary commissions above 5% to 15%. Test the invoice against what the member was told, under the price and value outcome (PRIN 2A.4).
- High. An appointed representative acting outside the principal’s permissions. That is unauthorised activity under section 19 of FSMA.
- High. A 2021 transfer-regulations amber flag, including a high-risk or overseas link. The statutory right to transfer depends on a MoneyHelper safeguarding appointment.
The full note is Financial Crime & Unauthorised Intermediary Funnels: Spotting the “Introducer” Red Flags.
Ongoing charges and fee-for-no-service
The ongoing advice retainer
Taking 0.50% to 1.00% a year as an ongoing adviser charge, without contemporaneous proof of an annual suitability review, breaches the price and value outcome (PRIN 2A.4) and the duty to avoid foreseeable harm (PRIN 2A.2).
A CRM status of “review completed”, or a valuation that went out automatically, is not that review. The file is tested on three points.
- Substance. Wrappers, asset allocation and any discretionary mandate were actually reconsidered under COBS 9 or COBS 9A.
- Capacity for loss. Changes in health, retirement timing or expenditure are recorded in pounds and pence.
- Cumulative drag. Adviser, platform, discretionary and transaction costs are reconciled to the service the client received.
The client who does not respond
Fees that keep leaving a disengaged client’s arrangement are a redress book, not an administration nuisance. A defensible control has three steps.
- More than one channel. Contact through the secure portal, email and post, each one recorded.
- A stop-clock. A stated point — often 60 to 90 days after the review was due — at which the ongoing charge is switched off at the platform.
- Vulnerability. Confirmation that silence was not cognitive impairment or bereavement, under PRIN 2A.6.
The four-tier file grade
Every file closes on one grade. The grade is the determination, not a commentary on how hard the case was.
| Tier | Determination | What the file shows |
|---|---|---|
| 1. Suitable | Pass | Suitability is evidenced, the fact-find checks out, costs reconcile, and the client's confirmation is on the file. Defensible before the FCA, a Skilled Person and the Ombudsman. |
| 2. Minor remedial | Pass with remediation | The advice is sound. An administrative gap remains, such as a missing note or unconfirmed essential expenditure. The correction is tracked to completion. |
| 3. Unclear | Action required | Critical information is missing: ceding scheme rules, or capacity for loss with no record. Execution waits until the gap is closed. |
| 4. Unsuitable / detriment | Fail | A material failure: an unevidenced defined benefit transfer, an unvetted non-standard asset, or ongoing fees taken with no service. Fees stop, and remediation or redress is modelled. |
When the review is commissioned
- Before the money moves. Defined benefit transfers, non-standard SIPP assets, complex switches, and any case involving a vulnerable client.
- On a retainer. A monthly or quarterly sample, often five to twenty files per adviser each year, so the book stays audit-ready.
- Before a purchase. A target client bank, read for unserviced cohorts, advice-gap liabilities and recurring fees that lack a service.
- Before the supervisor asks. A historical cohort, tested ahead of an FCA data request, a Skilled Person review, or the board’s annual assessment.
How the file moves through review
1. Secure ingestion
Fact-finds, suitability reports, research packs, illustrations and AML records come in through an encrypted portal.
Then
2. Forensic interrogation
The record is read against COBS 9 and 9A, COBS 19, SYSC and PRIN 2A, on a calibrated scorecard.
Then
3. Real-terms stress-test
Downside loss is stated in pounds against essential spending and the cash actually available. This is the standard-of-living test.
Then
4. The determination
The report, usually within three to five working days, gives the grade, the remedial actions, and any red-flag escalation.
Then
5. Executive MI
File results are aggregated into quarterly management information the compliance committee and the board can rely on.
Summary
A defensible advice file is a contemporaneous record that survives a scoring tool, a capital calculation and a question about what the client paid for. The tests above are how defined benefit transfers, high-risk SIPPs and ongoing charges are read before the regulator, a Skilled Person or the Ombudsman reads them first.
Where the need is pre-sale clearance, a sampling retainer, or capacity for a past-business review, the place to start is the contact page.
Other insights
Financial Crime & Unauthorised Intermediary Funnels: Spotting the "Introducer" Red Flags
20 October 2026 , 6 min
The unregulated introducer model has driven SIPP provider failures and FSCS levies for two decades. Toxic funnels leave repeatable footprints that a structured red-flag audit can find.
Read article
Decumulation Friction: Phased Drawdown, In-Specie Transfers, and Illiquid Asset Traps — When It's Not So Straightforward
18 October 2026 , 6 min
In bespoke SIPPs holding property, unquoted equities or loan notes, pension flexibility is often theoretical. Crystallising benefits without a clear cash pathway creates operational drag, Consumer Duty breaches and complaints.
Read article
SIPP Borrowing & Commercial Property: Navigating the 50% Net Asset Cap and Connected-Party Leases
16 October 2026 , 5 min
Commercial property in a SIPP or SSAS sits under intense HMRC scrutiny. Breaching the 50% borrowing cap or tolerating connected-party rent arrears triggers punitive unauthorised payment charges.
Read article
Auditing Illiquidity and Valuation: The 30-Day Standard Asset Test Under SIPP Capital Adequacy Rules
14 October 2026 , 5 min
Labelling illiquid investments as standard assets suppresses a SIPP operator's capital requirement on paper. A forensic liquidity audit tests every asset against the 30-day gate.
Read article
SIPP Operator Due Diligence: Lessons from Adams v Options UK and the FCA Due Diligence Framework
12 October 2026 , 6 min
An execution-only disclaimer no longer shields a SIPP operator. After Adams v Options UK, reviewers ask whether the operator actively vetted the asset and the distribution channel before accepting it.
Read article
Abridged Advice vs Full Advice: Managing the Boundary Under COBS 19.1A
10 October 2026 , 5 min
Abridged advice can only ever produce two outcomes. Firms that blur the boundary into full advice risk breaching the contingent charging ban and issuing invalid Section 48 confirmations.
Read article
The DBAAT File Audit: Scoring Section 166 Redress Liabilities Before the Regulator Arrives
8 October 2026 , 5 min
The FCA reviews defined benefit transfer books with the DBAAT, not narrative impressions. A single gate failure on capacity for loss or information gathering can render the whole advice outcome unsuitable.
Read article
Unpacking Scheme Solvency: Handling Employer Covenants and PPF Nuance Under COBS 19.1.2DG
6 October 2026 , 4 min
Employer covenant weakness is often used to justify an otherwise unsuitable defined benefit transfer. COBS 19.1.2DG sets clear limits on how scheme solvency and PPF compensation are presented.
Read article
Stress-Testing the APTA & TVC: When Stochastic Cashflow Models Cross into "Wishful Thinking"
2 October 2026 , 5 min
Cashflow modelling is one of the most heavily scrutinised parts of a defined benefit transfer file. Optimistic stochastic models are often used to paper over structural cracks in transfer sustainability.
Read article
Consumer Duty Governance, Outcome MI and SM&CR Assurance
1 November 2026 , 11 min
Principle 12 asks for contemporaneous proof of customer outcomes. Activity statistics, dealing SLAs and a green dashboard do not provide it.
Read article
Decumulation Telemetry: Tracking SIPP Drawdown Lag as Foreseeable Harm
1 November 2026 , 9 min
A 48-hour dealing SLA can hide three or four weeks between a drawdown instruction and cleared money. That gap is a foreseeable-harm question under PRIN 2A.2.
Read article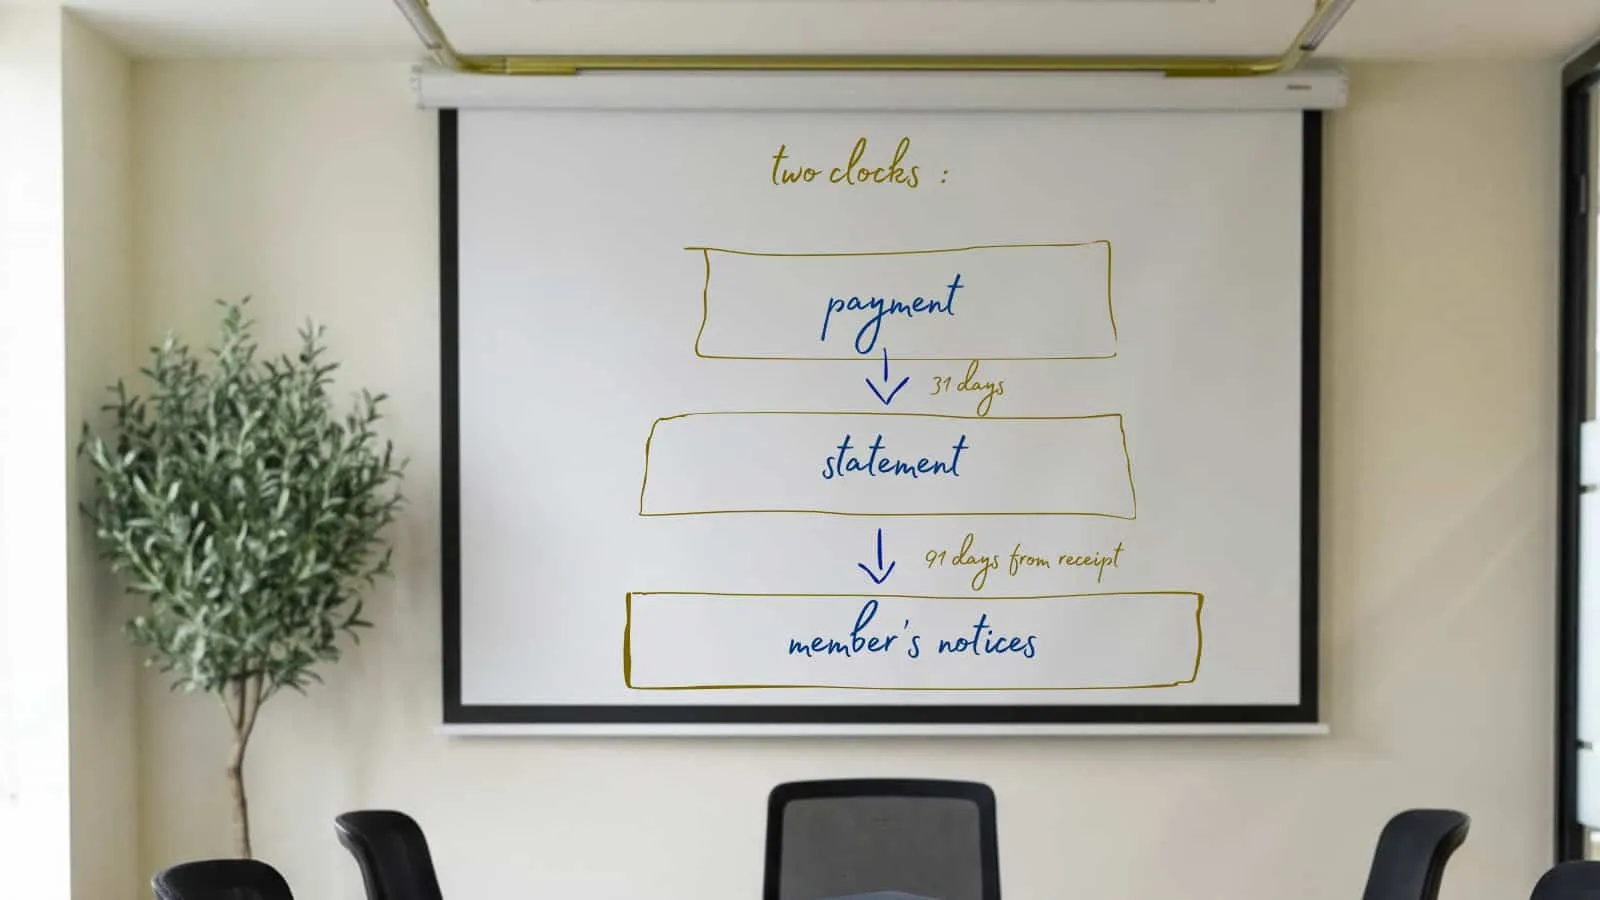
The 31-Day MPAA Trap: Monitoring Statutory Trigger Disclosures in Flexi-Access Drawdown
1 November 2026 , 8 min
The Money Purchase Annual Allowance starts when taxable income is paid. The scheme administrator then has 31 days to tell the member. A document sitting in a portal is not that notice.
Read article
Fixed-Fee Erosion in Low-Value SIPP Pots: When Administration Fees Breach Fair Value
1 November 2026 , 8 min
A flat trustee fee that is trivial on a large SIPP can consume several % of a residual pot. PRIN 2A.4 looks at that cohort, not the average charge across the book.
Read article
Strategic FOS Defence, Dispute Resolution and Forensic Redress Modelling
27 October 2026 , 11 min
A practical account of high-stakes complaints: eight-week final responses, DISP 2.8 time-bars, preliminary-view rebuttals and redress modelled to the FCA benchmarks.
Read article
The Jurisdictional Shield: Enforcing DISP 2.8 Time Limits Against Stale Claims
26 October 2026 , 4 min
A complaint about advice given eight or ten years ago is often a jurisdiction question before it is a suitability question. DISP 2.8.2R is the test.
Read article
Rebutting the Ombudsman Investigator's Preliminary View: The Mechanics of an Effective Escalation
26 October 2026 , 4 min
An adverse preliminary view is not the decision. It is a document that can be taken apart where it uses hindsight or misreads the product.
Read article
The 8-Week Final Response Letter: Drafting for the Ombudsman, Not Just the Client
26 October 2026 , 4 min
The eight-week letter is the brief the Ombudsman will read. An apology that concedes a breach is very hard to row back.
Read article
Attitude to Risk vs Capacity for Loss: Winning the Battle of Contemporaneous Evidence
26 October 2026 , 4 min
A signed risk questionnaire does not answer a complaint about losses. Capacity for loss, recorded at the time, does.
Read article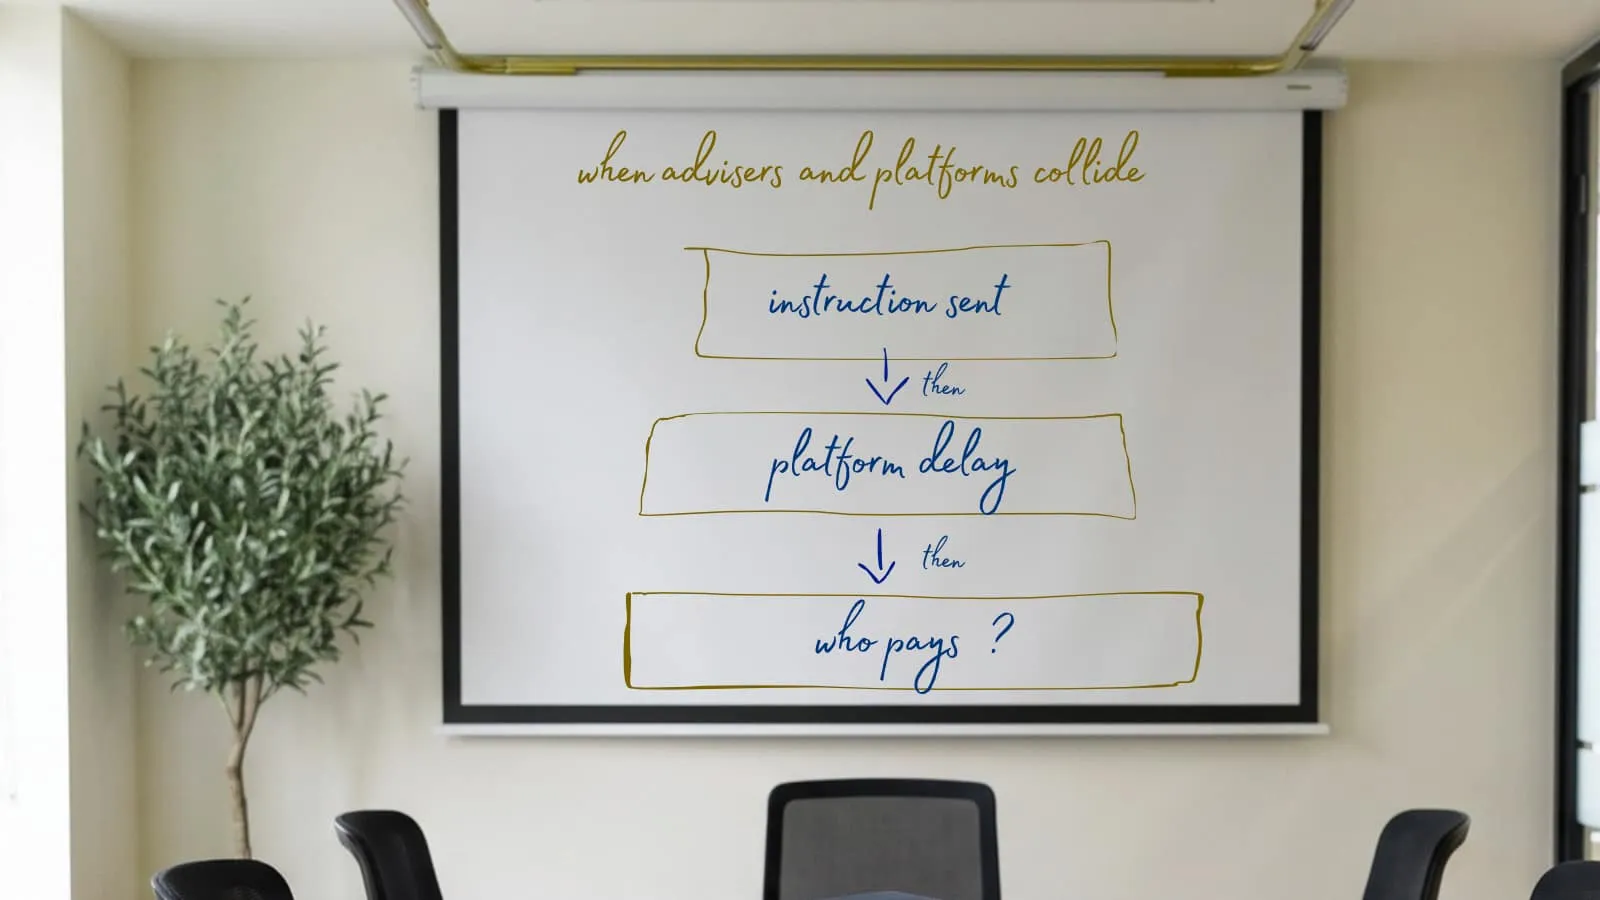
When Advisers and Platforms Collide: Defending the Boundaries of Intermediary Responsibility
26 October 2026 , 4 min
A dealing backlog at the platform is not, by itself, an advice failure. The timeline shows who had the instruction, and when.
Read article
Halting Regulatory Retrospectivity: Defending Legacy Advice Against Post-Consumer Duty Claims
26 October 2026 , 4 min
Consumer Duty language in a complaint about pre-2023 advice does not rewrite the rules that applied on the day. DISP 3.6.4R keeps the case in its own time.
Read article
SIPP Custody vs Advisory Due Diligence: Applying Adams v Options UK to Intermediary Disputes
26 October 2026 , 5 min
When a SIPP asset fails, the operator's duty and the adviser's duty are not the same duty. Adams v Options UK does not merge them.
Read article
Turning FOS Casework into Consumer Duty Root-Cause MI: Complaints as Governance Telemetry
26 October 2026 , 4 min
A falling complaint count is not root-cause information. DISP 1.3 and the Consumer Duty board report ask what kept going wrong.
Read article
Beyond Simple Cash Differences: Why Generalist Accounting Fails FCA Redress Benchmarks (FG17/9)
26 October 2026 , 4 min
Money in minus money out is not a pension redress calculation. FG17/9 and DISP App 1 require the position the client would have been in.
Read article
The Month 1 Emergency Tax Trap: Assessing True Detriment vs Temporary Cashflow Drag Under Code 1257L M1
26 October 2026 , 4 min
A Month 1 tax code can withhold thousands on a first drawdown payment. Most of that money is reclaimable. It is not automatically redress.
Read article
Benchmarking Distress and Inconvenience: Defending Against Exaggerated Non-Financial Detriment Claims
26 October 2026 , 4 min
A demand for £5,000 to £10,000 of upset, attached to an ordinary delay, sits outside the Ombudsman's published bands. The log is what places the case.
Read article