Financial Crime & Unauthorised Intermediary Funnels: Spotting the "Introducer" Red Flags
Anatomy of a toxic funnel: spotting unauthorised intermediary red flags and Section 27 FSMA liabilities
The single greatest driver of SIPP provider failures and FSCS compensation levies over the last two decades has been the unregulated introducer model.
From historical scams involving offshore storage pods and unregulated forestry schemes to contemporary boiler-room clone funnels, the operational structure remains consistent: unregulated lead generators identify retail pension savers through aggressive social media marketing, cold-call funnels, or “free pension review” hooks, and funnel them into friendly SIPP providers to execute toxic investments.
Under Section 27 and Section 28 of FSMA, alongside the Occupational and Personal Pension Schemes (Conditions for Transfers) Regulations 2021, scheme administrators and advisers sit under strict statutory duties to identify, flag, and refuse transfers originating from compromised distribution chains.
When compliance officers audit intermediary networks and onboarding registers, identifying these red flags is essential to protect the firm from past-business remediation orders and civil litigation.
The File Review Failure: Blind Acceptance of High-Risk Inflows
Compliance audits consistently highlight cases where intermediary onboarding controls existed only on paper.
Turning a blind eye to Appointed Representatives (ARs)
Onboarding business from an AR operating completely outside the scope of their principal’s agreed regulatory permissions (for example, an AR authorised only for general insurance introducing complex commercial property SIPPs).
The “secondary lead-generator” blind spot
Accepting business from an authorised IFA firm while failing to check where the IFA sourced the client. In reality, the IFA was acting merely as a “rubber-stamping factory” for an overseas, unregulated marketing company.
Overlooking the statutory scam flags
Failing to raise Red or Amber Flags under the 2021 Pension Transfer Regulations when transfer requests feature unregulated offshore assets, aggressive turnaround pressure, or third parties offering to help members access cash before age 55.
Forensic Intermediary Vetting: The Compliance Red-Flag Matrix
When auditing new or historical distribution funnels, compliance officers apply a structured red-flag matrix across all onboarding channels.
| Red flag | Description | Risk level | Statutory / regulatory threat | Audit action required |
|---|---|---|---|---|
| 1. Unregulated lead generator | Providing completed SIPP forms directly to the provider. | Critical | Section 27 FSMA unenforceability (agreement is legally invalid; full redress due). | Immediate refusal of business; freeze relationship; report to FCA Intelligence. |
| 2. Batch submissions | 10+ identical transfer requests into the same esoteric underlying asset within days. | Critical | "SIPP factory" / collusive advice model; breaches SYSC 6 systems and controls. | Halt pipeline; trigger forensic past-business review across all cohort cases. |
| 3. Abnormal commission / fee sharing | Intermediary fees exceeding 5%–15% deducted from transferred capital. | High | Consumer Duty price and value (PRIN 2A.4) and FCA bribery / inducement rules. | Request detailed invoice justification; test fee transparency against member disclosures. |
| 4. Appointed Representative (AR) permission scope | Submitting pension cases outside the principal's explicit permission schedule. | High | Unauthorised activity under Section 19 FSMA (advice is legally ultra vires). | Verify the principal's written confirmation; reject the application if permissions do not cover the transaction. |
| 5. Overseas connection / non-UK residency | UK retail member transferring into a UK SIPP holding assets based in opaque jurisdictions. | High | 2021 Transfer Regulations Amber/Red Flag and serious financial crime vulnerability. | Mandatory referral to MoneyHelper; stop the transfer if statutory Red Flag criteria are met. |
The Forensic Audit Trail: What Regulators Expect
To demonstrate robust financial crime and intermediary oversight under FCA Principle 2 and SYSC 6.1.1R, the firm’s compliance files must show continuous monitoring, not just a one-off Companies House search at initial onboarding.
Source of wealth / source of funds (SoW/SoF) corroboration
Files must hold verifiable evidence tracing the legitimate origins of the transferred capital, confirming funds do not derive from high-risk pension release or unapproved loan-back structures.
Automated KYC / UBO verification
Interrogating the Ultimate Beneficial Ownership (UBO) of all corporate entities involved in the distribution chain. If an introducer, fund manager, and SIPP marketing firm share common directors or shadow shareholders, the undisclosed conflict of interest must be flagged immediately.
Testing transfer regulation flags (the MoneyHelper barrier)
Auditors check whether transfer administrators properly applied the 2021 Transfer Regulations. If an Amber Flag was present (such as high-risk investments or overseas connections), did the scheme administrator halt the transfer until the member provided an official MoneyHelper safeguarding guidance certificate? If an administrator completed the transfer without that certificate, the statutory right to transfer was absent, exposing the ceding scheme to full restoration claims.
Key Takeaway for Compliance Directors
Toxic introducers do not operate in secret; they leave obvious, repeatable operational footprints. Auditing distribution pipelines for volume anomalies, fee spikes, and intermediary scope creep is the only way SIPP providers and advice networks can prevent catastrophic balance-sheet liabilities and systemic enforcement actions.
Other insights
Forensic File Reviews, Complex Pension Scrutiny and Ongoing Servicing Audits
22 October 2026 , 12 min
A forensic file review tests defined benefit transfers, high-risk SIPPs and ongoing charges against COBS, SYSC and the Consumer Duty, before a regulator or ombudsman does.
Read article
Decumulation Friction: Phased Drawdown, In-Specie Transfers, and Illiquid Asset Traps — When It's Not So Straightforward
18 October 2026 , 6 min
In bespoke SIPPs holding property, unquoted equities or loan notes, pension flexibility is often theoretical. Crystallising benefits without a clear cash pathway creates operational drag, Consumer Duty breaches and complaints.
Read article
SIPP Borrowing & Commercial Property: Navigating the 50% Net Asset Cap and Connected-Party Leases
16 October 2026 , 5 min
Commercial property in a SIPP or SSAS sits under intense HMRC scrutiny. Breaching the 50% borrowing cap or tolerating connected-party rent arrears triggers punitive unauthorised payment charges.
Read article
Auditing Illiquidity and Valuation: The 30-Day Standard Asset Test Under SIPP Capital Adequacy Rules
14 October 2026 , 5 min
Labelling illiquid investments as standard assets suppresses a SIPP operator's capital requirement on paper. A forensic liquidity audit tests every asset against the 30-day gate.
Read article
SIPP Operator Due Diligence: Lessons from Adams v Options UK and the FCA Due Diligence Framework
12 October 2026 , 6 min
An execution-only disclaimer no longer shields a SIPP operator. After Adams v Options UK, reviewers ask whether the operator actively vetted the asset and the distribution channel before accepting it.
Read article
Abridged Advice vs Full Advice: Managing the Boundary Under COBS 19.1A
10 October 2026 , 5 min
Abridged advice can only ever produce two outcomes. Firms that blur the boundary into full advice risk breaching the contingent charging ban and issuing invalid Section 48 confirmations.
Read article
The DBAAT File Audit: Scoring Section 166 Redress Liabilities Before the Regulator Arrives
8 October 2026 , 5 min
The FCA reviews defined benefit transfer books with the DBAAT, not narrative impressions. A single gate failure on capacity for loss or information gathering can render the whole advice outcome unsuitable.
Read article
Unpacking Scheme Solvency: Handling Employer Covenants and PPF Nuance Under COBS 19.1.2DG
6 October 2026 , 4 min
Employer covenant weakness is often used to justify an otherwise unsuitable defined benefit transfer. COBS 19.1.2DG sets clear limits on how scheme solvency and PPF compensation are presented.
Read article
Stress-Testing the APTA & TVC: When Stochastic Cashflow Models Cross into "Wishful Thinking"
2 October 2026 , 5 min
Cashflow modelling is one of the most heavily scrutinised parts of a defined benefit transfer file. Optimistic stochastic models are often used to paper over structural cracks in transfer sustainability.
Read article
Consumer Duty Governance, Outcome MI and SM&CR Assurance
1 November 2026 , 11 min
Principle 12 asks for contemporaneous proof of customer outcomes. Activity statistics, dealing SLAs and a green dashboard do not provide it.
Read article
Decumulation Telemetry: Tracking SIPP Drawdown Lag as Foreseeable Harm
1 November 2026 , 9 min
A 48-hour dealing SLA can hide three or four weeks between a drawdown instruction and cleared money. That gap is a foreseeable-harm question under PRIN 2A.2.
Read article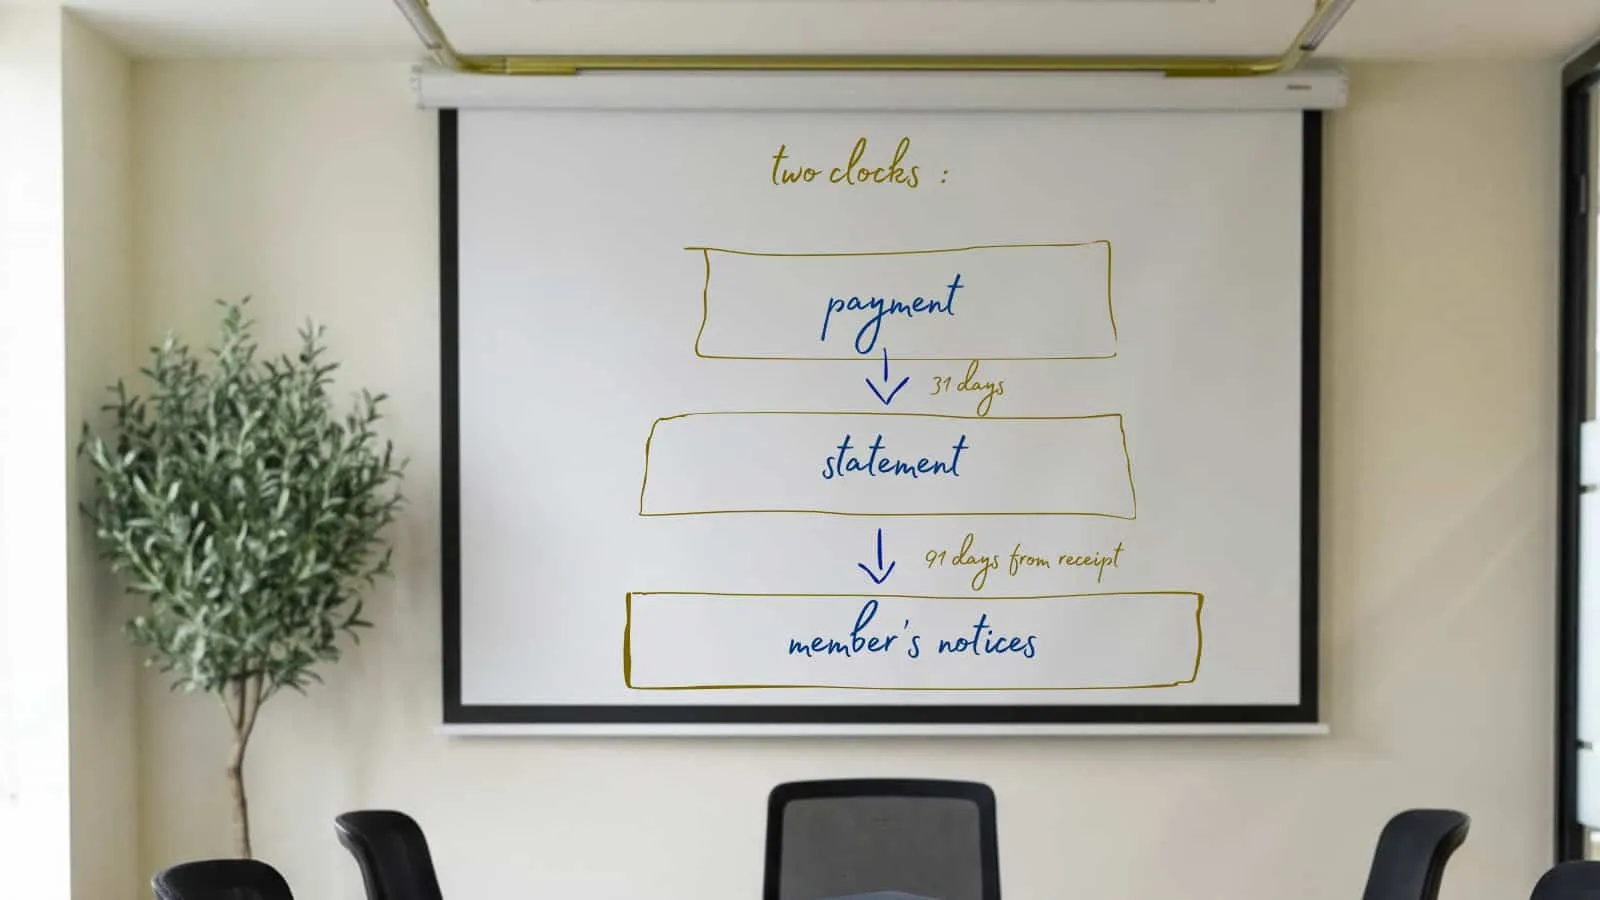
The 31-Day MPAA Trap: Monitoring Statutory Trigger Disclosures in Flexi-Access Drawdown
1 November 2026 , 8 min
The Money Purchase Annual Allowance starts when taxable income is paid. The scheme administrator then has 31 days to tell the member. A document sitting in a portal is not that notice.
Read article
Fixed-Fee Erosion in Low-Value SIPP Pots: When Administration Fees Breach Fair Value
1 November 2026 , 8 min
A flat trustee fee that is trivial on a large SIPP can consume several % of a residual pot. PRIN 2A.4 looks at that cohort, not the average charge across the book.
Read article
Strategic FOS Defence, Dispute Resolution and Forensic Redress Modelling
27 October 2026 , 11 min
A practical account of high-stakes complaints: eight-week final responses, DISP 2.8 time-bars, preliminary-view rebuttals and redress modelled to the FCA benchmarks.
Read article
The Jurisdictional Shield: Enforcing DISP 2.8 Time Limits Against Stale Claims
26 October 2026 , 4 min
A complaint about advice given eight or ten years ago is often a jurisdiction question before it is a suitability question. DISP 2.8.2R is the test.
Read article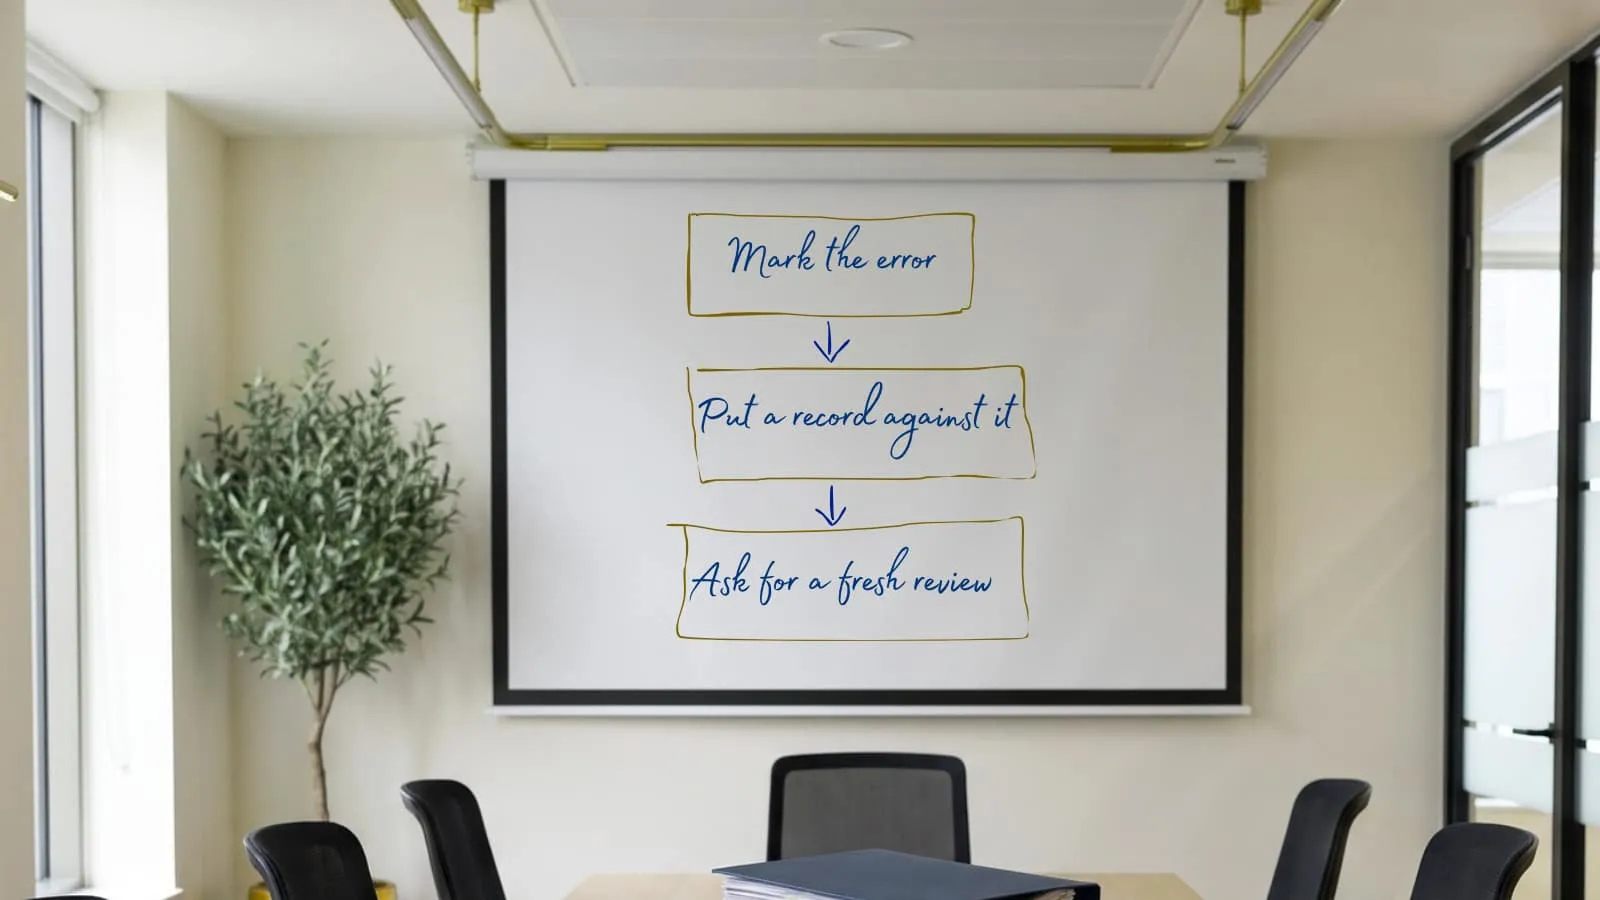
Rebutting the Ombudsman Investigator's Preliminary View: The Mechanics of an Effective Escalation
26 October 2026 , 4 min
An adverse preliminary view is not the decision. It is a document that can be taken apart where it uses hindsight or misreads the product.
Read article
The 8-Week Final Response Letter: Drafting for the Ombudsman, Not Just the Client
26 October 2026 , 4 min
The eight-week letter is the brief the Ombudsman will read. An apology that concedes a breach is very hard to row back.
Read article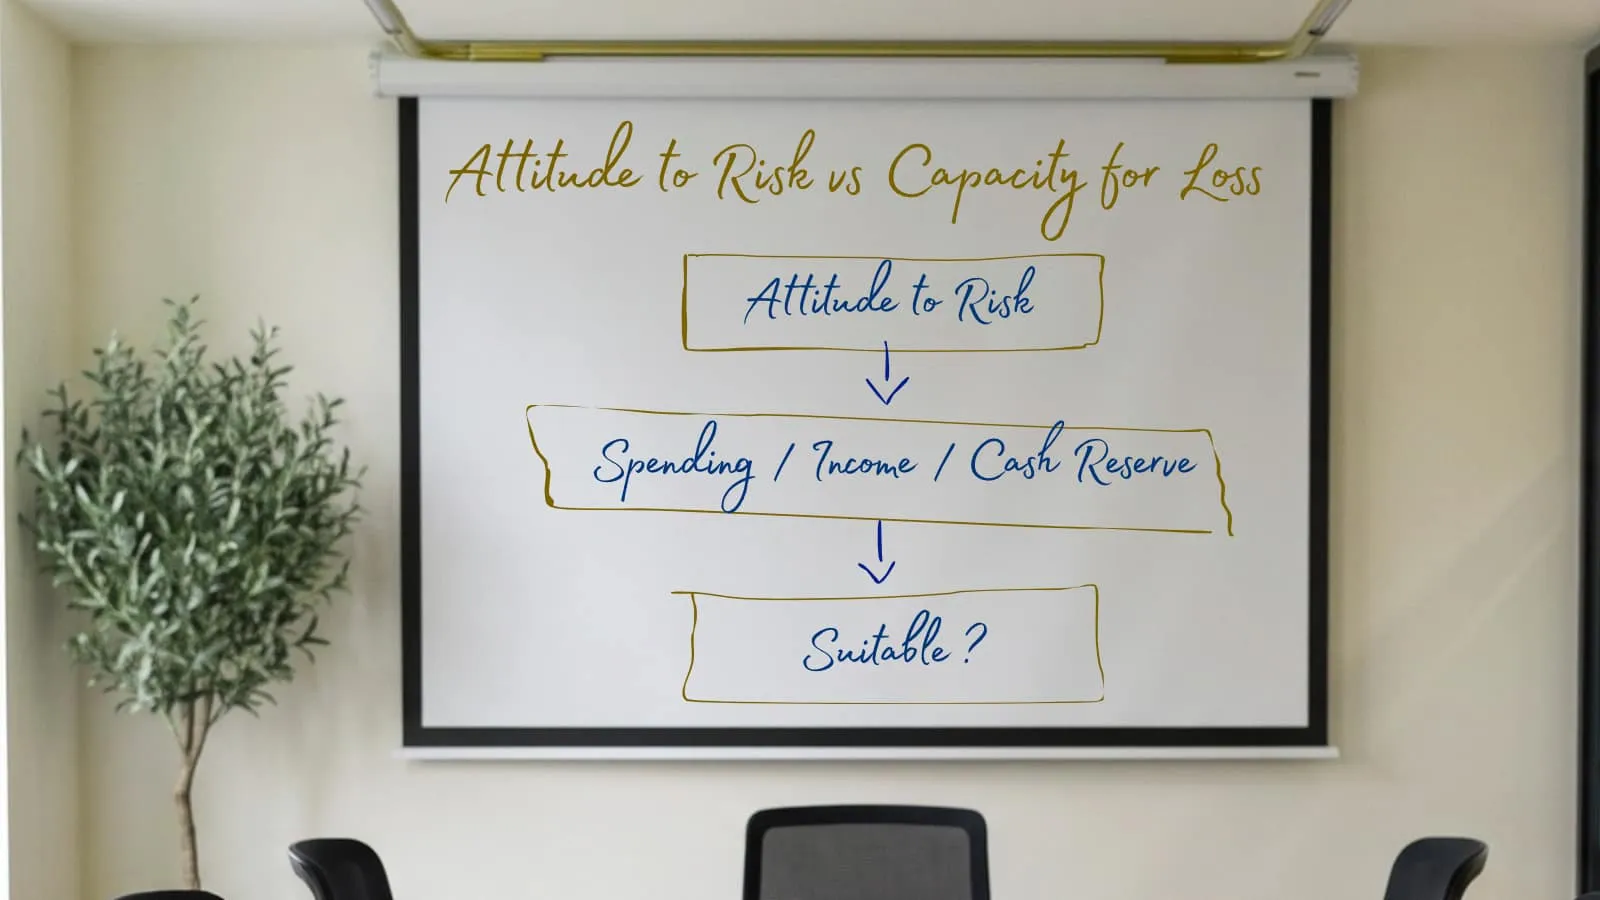
Attitude to Risk vs Capacity for Loss: Winning the Battle of Contemporaneous Evidence
26 October 2026 , 4 min
A signed risk questionnaire does not answer a complaint about losses. Capacity for loss, recorded at the time, does.
Read article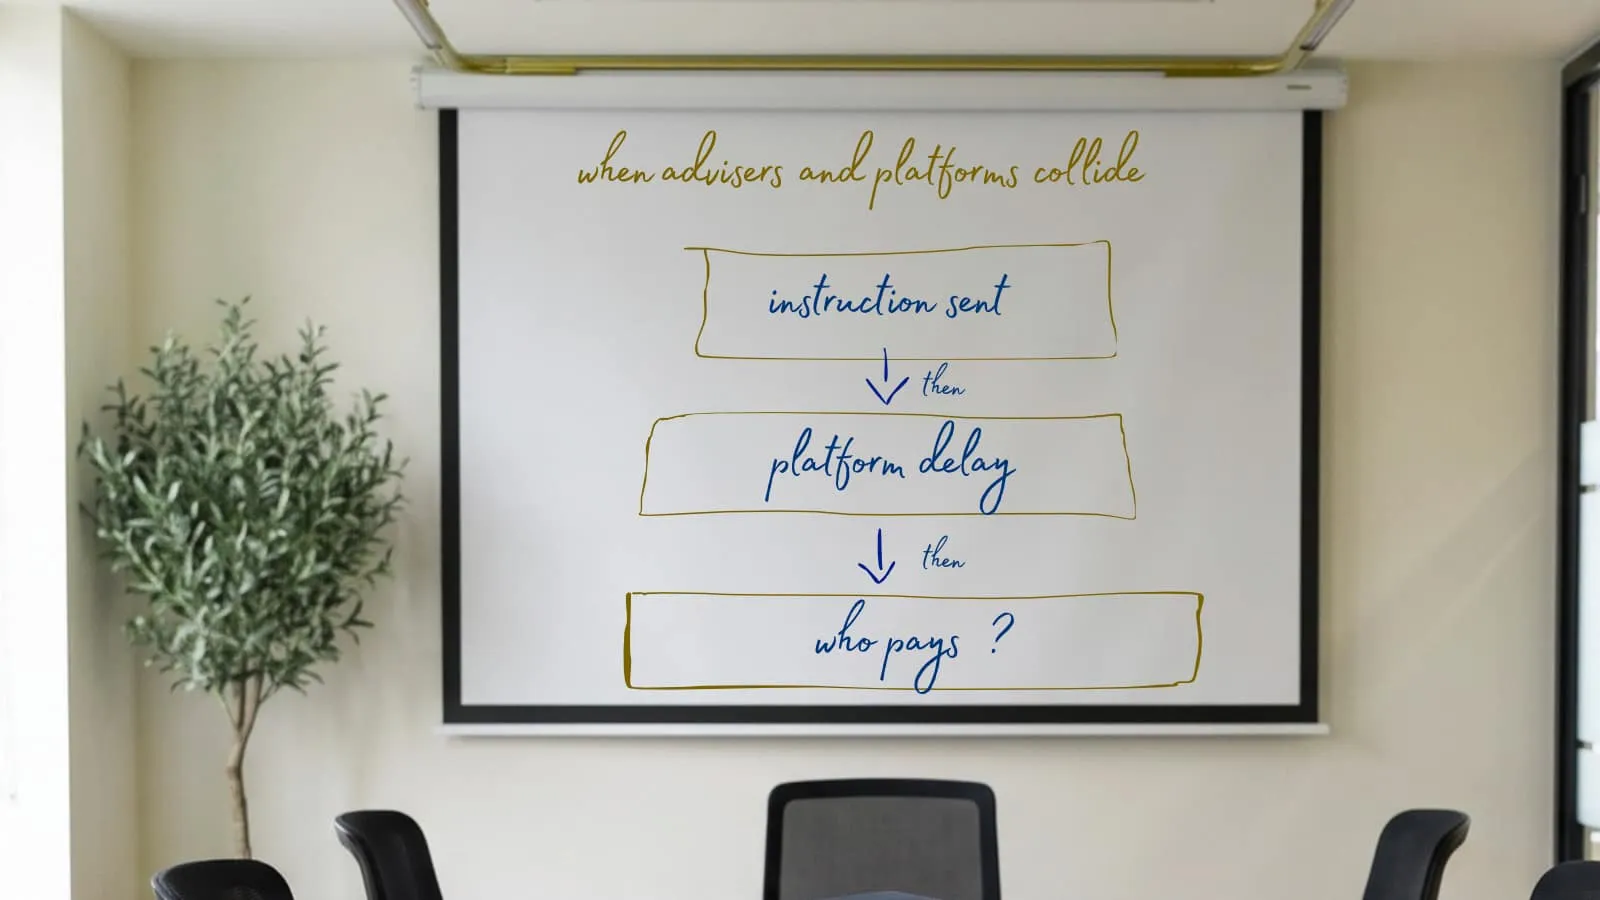
When Advisers and Platforms Collide: Defending the Boundaries of Intermediary Responsibility
26 October 2026 , 4 min
A dealing backlog at the platform is not, by itself, an advice failure. The timeline shows who had the instruction, and when.
Read article
Halting Regulatory Retrospectivity: Defending Legacy Advice Against Post-Consumer Duty Claims
26 October 2026 , 4 min
Consumer Duty language in a complaint about pre-2023 advice does not rewrite the rules that applied on the day. DISP 3.6.4R keeps the case in its own time.
Read article
SIPP Custody vs Advisory Due Diligence: Applying Adams v Options UK to Intermediary Disputes
26 October 2026 , 5 min
When a SIPP asset fails, the operator's duty and the adviser's duty are not the same duty. Adams v Options UK does not merge them.
Read article
Turning FOS Casework into Consumer Duty Root-Cause MI: Complaints as Governance Telemetry
26 October 2026 , 4 min
A falling complaint count is not root-cause information. DISP 1.3 and the Consumer Duty board report ask what kept going wrong.
Read article
Beyond Simple Cash Differences: Why Generalist Accounting Fails FCA Redress Benchmarks (FG17/9)
26 October 2026 , 4 min
Money in minus money out is not a pension redress calculation. FG17/9 and DISP App 1 require the position the client would have been in.
Read article
The Month 1 Emergency Tax Trap: Assessing True Detriment vs Temporary Cashflow Drag Under Code 1257L M1
26 October 2026 , 4 min
A Month 1 tax code can withhold thousands on a first drawdown payment. Most of that money is reclaimable. It is not automatically redress.
Read article
Benchmarking Distress and Inconvenience: Defending Against Exaggerated Non-Financial Detriment Claims
26 October 2026 , 4 min
A demand for £5,000 to £10,000 of upset, attached to an ordinary delay, sits outside the Ombudsman's published bands. The log is what places the case.
Read article